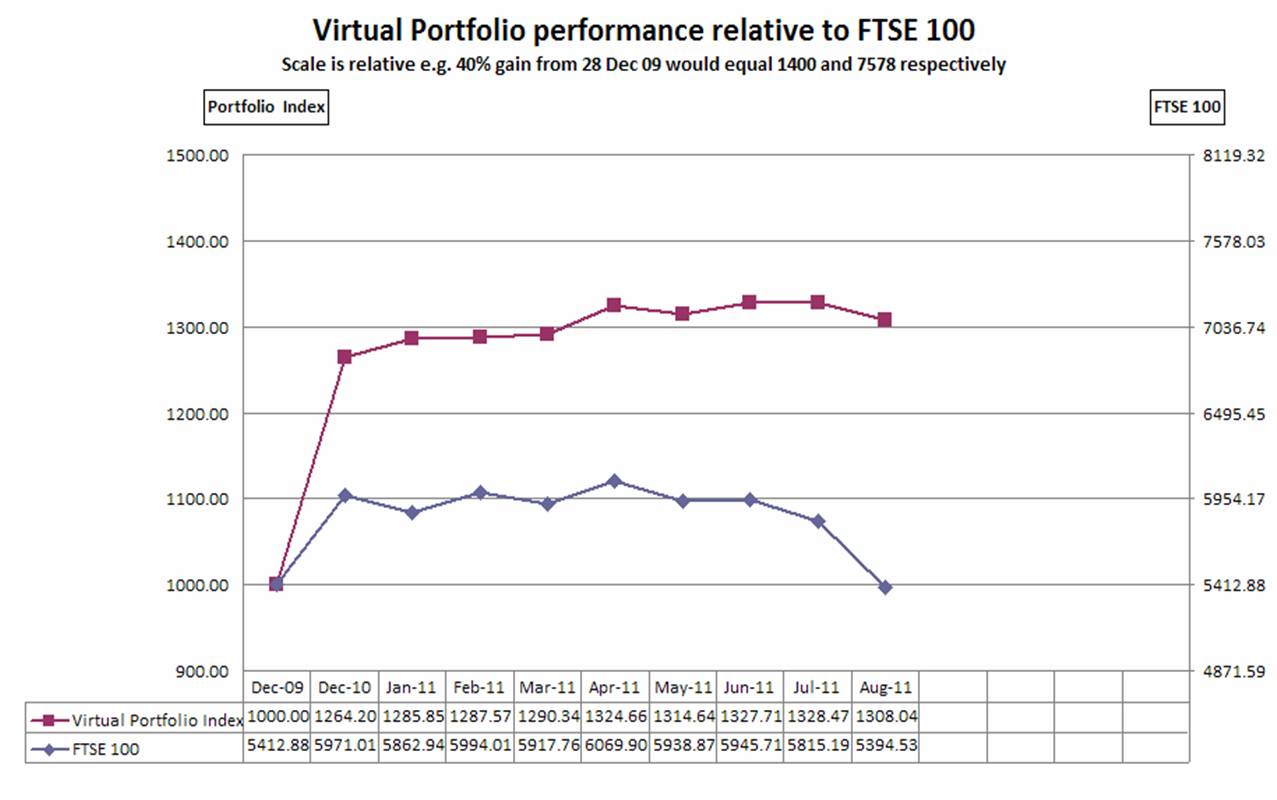
Well August was, and no doubt September will also be, a roller coaster of a month but, surprisingly the virtual portfolio ended August back in positive territory for 2011.
The index for the portfolio actually ended August on 1308.04, 3.47% up on its 2011 starting point of 1264.20 which continues to stand favourable comparison with the FTSE 100 which, at 5394.53, has ended the month still -0.34% against its 2009 year-end position and -9.65% year to date.
This is all despite the FTSE100 recovering from the intra-day low of 4801 seen on the 19th August.
Both the portfolio and the FTSE have again pulled back in the first 2 trading days of September following a disappointing US non-farm payrolls report which came through even worse than the already downgraded estimates, feeding further fears that the US is sliding back into recession.
Further impact news came through with the announcement that America's Federal Housing Finance Agency is suing 17 major banks for what is effectively the mis-selling of mortgage products to the tune of $200bn (£123bn) to the two state owned mortgage companies Freddie Mac and Fanny Mae.
The list includes RBS, Barclays, and HSBC, with RBS seemingly second only, in scale of misdemeanour, to JP Morgan Chase with a total of £18.5bn of mortgage products sold. More worry for the banks then and, in the case of RBS, for tax payers money.
Back to the portfolio though and what took place in August apart from my reaching for a tin hat. Well, in the shake out it initially fell by around 7% in the month and then recovered from an August low which hit approx. -2.5% year to date. Disappointing but, in context, bears little relation to the concerns and amplified fear in media news stories currently doing the rounds.
This has prompted me to make some additions and changes to the portfolio though:
- following a fall of around 20% I added to the portfolio's holding in Aviva although I wasn't even close to catching the August low point.
- Vodaphone also came in with its forecast 7% yield and the re-instated dividend from its investment in Verizon Wireless.
- Cisco was thrown out. Before the recent chaos I had made up my mind to keep Cisco and wait for a slow recovery but given the falls across the market my view has changed. Cisco was seemingly already at a bottom and hasn't fallen much further with the market. But, "better" shares with better prospects for recovery have since fallen to similar valuations. One such is General Electric which has been added to the portfolio and will show in September's update as a replacement for Cisco.
In other portfolio activity, Cisco gave up a last quarterly dividend of approx. 3.6p per share and National Grid also added to the portfolio's cash position with a dividend of 23.47p per share.
Its also worth noting that, if maintained, the forecast yield for the portfolio has increased relative to its value with the August additions.
| Virtual Portfolio - Merchant Adventurer's Index |
|
|
|
|
|
| Forecast | 1 month | YTD | 20 Months |
| % holding | Div. yield | % gain | % gain | % gain |
| R-R | 29.62% | 2.69% | -1.92% | 2.73% | 32.37% |
| National Grid | 19.13% | 6.31% | 4.02% | 12.30% | 14.42% |
| Inv. Perp. High Inc. *** | 6.77% | 0.00% | -5.61% | 0.01% | 12.06% |
| Aviva | 6.25% | 7.94% | -10.33% | -9.43% | -6.61% |
| BP | 4.12% | 4.36% | -12.70% | -13.55% | -7.55% |
| Apple ** | 4.23% | 0.00% | -0.37% | 14.46% | 95.36% |
| IG Group | 3.32% | 4.77% | 1.04% | -12.31% | 48.64% |
| William Hill | 2.95% | 4.06% | -2.25% | 32.22% | 32.00% |
| BG Group | 2.72% | 1.10% | -7.76% | 2.78% | 22.20% |
| Centrica | 2.63% | 5.10% | -2.41% | -9.77% | -5.26% |
| Morrisons | 2.55% | 3.72% | -0.65% | 8.00% | 14.21% |
| Scottish and Southern | 2.51% | 6.23% | -0.54% | 6.12% | 12.95% |
| Microsoft ** | 2.35% | 2.00% | -2.11% | -8.83% | 5.75% |
| Tesco | 2.12% | 4.13% | -1.26% | -5.09% | -5.09% |
| BAE Systems | 1.92% | 6.71% | -9.44% | -16.58% | -13.77% |
| Vodafone | 2.18% | 6.81% | -0.08% | -0.08% | -0.08% |
| Cisco ** | 1.61% | 0.48% | -1.74% | -26.38% | -27.76% |
| Cash | 3.02% | 0.00% | -55.27% | -46.03% |
|
|
|
|
|
|
|
| 100.00% | 3.79% |
|
|
|
|
|
|
|
|
|
|
| 1 Month | YTD | 20 Months |
| Virtual Portfolio gain (incl. Dividends) |
| -1.54% | 3.47% | 30.80% |
| FTSE gain (excl. Dividends) |
| -7.23% | -9.65% | -0.34% |
| - 1 month gain 5815.19 - 5394.53 |
|
|
|
|
| - YTD gain 5971.01 - 5394.53 |
|
|
|
|
| - 20 month gain 5412.88 - 5394.53 |
|
|
|
|
|
|
|
|
|
|
| Transactions: |
|
|
|
|
|
| 01/08/2011 | Dividends | Cisco @ 3.6p per share |
|
|
|
| 08/08/2011 | Buy | Aviva @ 341.5p |
|
|
| 09/08/2011 | Buy | Vodaphone @ 160.334p |
|
| 17/08/2011 | Dividends | Nat. Grid @ 23.47p per share |
|
|
|
| 30/08/2011 | Sell | Cisco @ $15.59 |
|
|
| 06/08/2011 | Fees | Account | management |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| Notes: |
|
|
|
|
|
| * US Dividends are adjusted for exchange rate and 15% withholding tax) |
|
| ** Sterling : Dollar exchange rate = £1: $1.6267 as at 31/08/11 |
|
|
| *** Invesco Perpetual Accumulation units (i.e. Dividends re-invested) |
|
Moving onto the chart comparing the Portfolio index to that of the FTSE100, the divergence of the 2 indexes continues (thankfully so in the current chaos).
Significantly, the FTSE's performance has actually forced me to amend the chart with the addition of a lower segment to reflect its fall below the 2009 end point (and starting point for the comparison).
 |
| Click to enlarge, back button to return. |
Looking ahead, there is a key point coming up (no, not UK interest rates), as the US Federal Open Market Committee meet up for September with the main discussion expected to be around what action, if any, should be taken to maintain/re-ignite the US economic recovery.
September also brings the 10th Anniversary of 9/11.
Whatever the outcome, it looks like it will remain a bumby ride for the foreseeable.
Tactically I am actually weighing the merits of adding more funds to the portfolio in order to take advantage (if it is an advantage!), of the current valuations.
Only time will tell if this is the case.
Related articles:
- www.citywire.co.uk: FTSE sinks 2.3% as markets twist on dismal US jobs report
- www.freep.com: Jobs report wipes out S&P's gain
Links to previous Portfolio updates:
- May 2011: Portfolio Update
- April 2011: Portfolio Update